

Estate planning documents like a Will, Power of Attorney, and Personal Medical Directive are incredibly powerful - but they don't do everything. There are estate planning measures that need to be taken in addition to these documents that people may or may not be aware of. An example of one of these estate planning measures is ensuring your digital legacy can be preserved after your death.
What is a digital legacy? For most Canadians that includes Facebook photos. I say Canadians because this is a Canadian blog, but also because Canadians love Facebook; 77% of Canadians have a Facebook account (compare that with 68% in the United States).
I personally have thousands of photos on Facebook; they chronicle important life events from my law school graduation to the birth of my first child. To say these photos are absolutely precious is an understatement. Losing these photos would be devastating, but imagine if I passed away and my family couldn't view or access them.

Unfortunately, even if you have a Will, Facebook will not allow your executor access to your account. There have been multiple, extremely sad news reports of families trying to gain access to a deceased person's Facebook account - all ending with Facebook refusing the request for privacy reasons. Facebook also has a contract with you via the user agreement you clicked to accept; this is a contract that dies when you do (pardon the pun). This means, your Facebook account (along with many other social media and other online accounts) are estate planning items that need to be handled outside of the traditional estate planning documents.
How do you do this?
With Facebook, you set a legacy contact on your Facebook account. A legacy contact is a person on your friends list who looks after your account if it's memorialized. An account changes to a memorialized account after Facebook becomes aware of your death (likely through your legacy contact).
A legacy contact can...
(1) accept friend requests on behalf of a memorialized account;
(2) pin a tribute post to the profile and change the profile picture and cover photo; and
(3) If your settings allow it, they can download account content (i.e. photos).
I've outlined the steps for doing on your browser below. The instructions are similar for mobile devices.
Step (1)
Go to your Facebook account settings. On mobile go to "Menu" and scroll down to "Settings & Privacy" - expand it and select "Settings".

Step (2)
Under "General" you should be able to see "Memorialisation Settings". Click on the "Edit" button. On mobile select "Personal Information" then select "Manage Account".
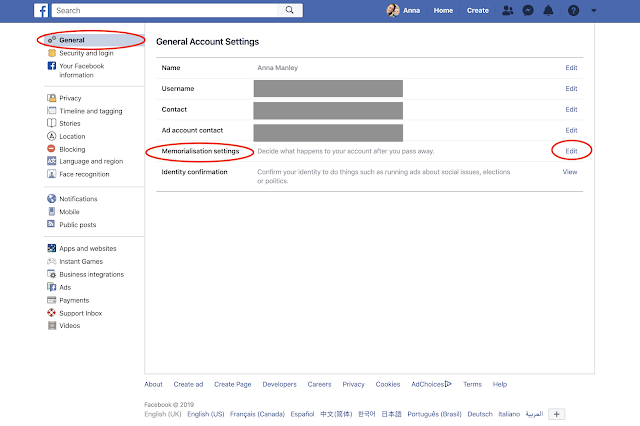
Step (3)
Enter in the name of someone you trust on your Facebook friends list. This person doesn't necessarily need to be your executor (if you have appointed one), but remember they will be the only one with access to your Facebook account after you pass away. Make sure it's someone who you trust to follow through on your wishes... also... tell them what your wishes actually are.
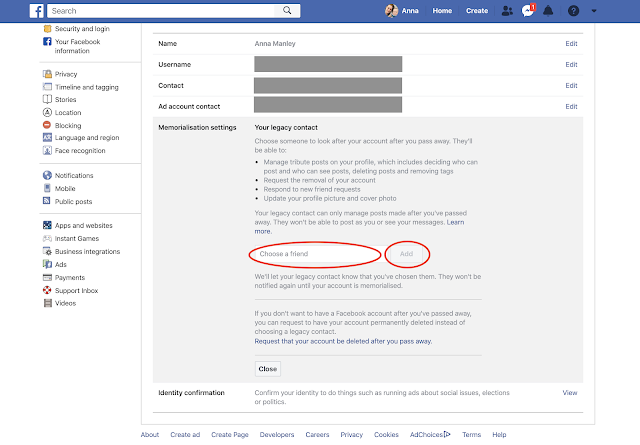
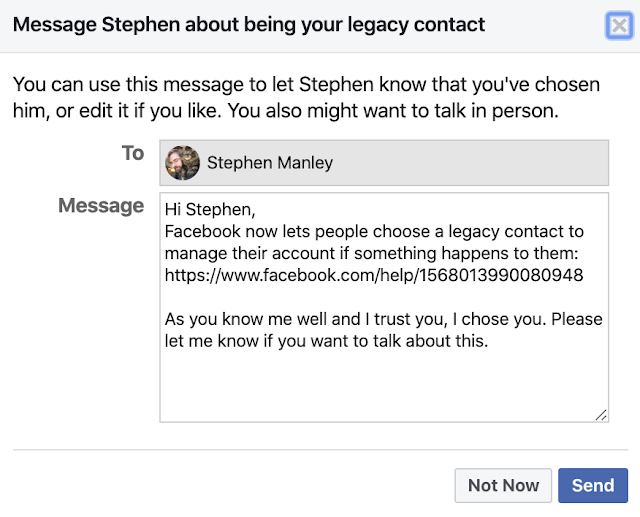
Once you select your legacy contact, a window will pop up where you can send them a message to let your legacy contact know that they've been appointed. I appointed my spouse, but you can appoint any person on your friends list. As with your executor, it's best to choose a person who will give effect to your wishes. You can even put those wishes in the message you send when you appoint them.
You can also select a yearly reminder settling where Facebook will automatically remind you who your legacy contact is and give you the option to change the friend who fills this roll.
Another option you can select on the "Memorialisation Settings" page. You can either allow your legacy contact to download what you have on Facebook. This is a good option to select because then your legacy contact can download all your photos in order to preserve them offline.

Overall, the Facebook legacy contact option is a necessary part of the estate planning process that occurs outside of your Will and other estate planning documents. For anybody with a digital presence, considering what is covered by your Will and what isn't is an important part of ensuring your most precious assets are safe for your family to cherish even after you're gone.
What is a digital legacy? For most Canadians that includes Facebook photos. I say Canadians because this is a Canadian blog, but also because Canadians love Facebook; 77% of Canadians have a Facebook account (compare that with 68% in the United States).
I personally have thousands of photos on Facebook; they chronicle important life events from my law school graduation to the birth of my first child. To say these photos are absolutely precious is an understatement. Losing these photos would be devastating, but imagine if I passed away and my family couldn't view or access them.

Unfortunately, even if you have a Will, Facebook will not allow your executor access to your account. There have been multiple, extremely sad news reports of families trying to gain access to a deceased person's Facebook account - all ending with Facebook refusing the request for privacy reasons. Facebook also has a contract with you via the user agreement you clicked to accept; this is a contract that dies when you do (pardon the pun). This means, your Facebook account (along with many other social media and other online accounts) are estate planning items that need to be handled outside of the traditional estate planning documents.
How do you do this?
With Facebook, you set a legacy contact on your Facebook account. A legacy contact is a person on your friends list who looks after your account if it's memorialized. An account changes to a memorialized account after Facebook becomes aware of your death (likely through your legacy contact).
A legacy contact can...
(1) accept friend requests on behalf of a memorialized account;
(2) pin a tribute post to the profile and change the profile picture and cover photo; and
(3) If your settings allow it, they can download account content (i.e. photos).
I've outlined the steps for doing on your browser below. The instructions are similar for mobile devices.
Step (1)
Go to your Facebook account settings. On mobile go to "Menu" and scroll down to "Settings & Privacy" - expand it and select "Settings".

Step (2)
Under "General" you should be able to see "Memorialisation Settings". Click on the "Edit" button. On mobile select "Personal Information" then select "Manage Account".

Step (3)
Enter in the name of someone you trust on your Facebook friends list. This person doesn't necessarily need to be your executor (if you have appointed one), but remember they will be the only one with access to your Facebook account after you pass away. Make sure it's someone who you trust to follow through on your wishes... also... tell them what your wishes actually are.

Once you select your legacy contact, a window will pop up where you can send them a message to let your legacy contact know that they've been appointed. I appointed my spouse, but you can appoint any person on your friends list. As with your executor, it's best to choose a person who will give effect to your wishes. You can even put those wishes in the message you send when you appoint them.

You can also select a yearly reminder settling where Facebook will automatically remind you who your legacy contact is and give you the option to change the friend who fills this roll.
Another option you can select on the "Memorialisation Settings" page. You can either allow your legacy contact to download what you have on Facebook. This is a good option to select because then your legacy contact can download all your photos in order to preserve them offline.

Overall, the Facebook legacy contact option is a necessary part of the estate planning process that occurs outside of your Will and other estate planning documents. For anybody with a digital presence, considering what is covered by your Will and what isn't is an important part of ensuring your most precious assets are safe for your family to cherish even after you're gone.
 |
| This post was written by Anna Manley. If you'd like to contact Anna you can send her an email: anna@manleylaw.ca |
Whether you're a first time home buyer or this isn't your first rodeo, the process of buying a home can be intimidating. There's a lot of jargon and a lot of legalese, but the most daunting question of all is:
How much is this going to cost me?
Fair question. You've worked hard to save the money for a downpayment on a house - now it's time for you to take the plunge and you're worried about surprises.
To make the whole process a little bit less intimidating, we've broken down the fees associated with a real estate transaction (from the buyer's side) so you can have an idea of how much the whole deal will actually cost.
Let's handle this with a case study.
Buyers: Linda & Greg
Linda and Greg are a young couple who just moved back from Alberta to start a family in Cape Breton. They found a perfect house in Sydney River (for $200,000) and already have plans for a fence for the dogs. They've saved to buy the house and only need a mortgage for $75,000. Let's say, for the sake of this post, that there was no adjustment made to the original purchase price. Linda and Greg's fees on the transaction (on top of the purchase price) will be:
Deed Registration Fee ($100)
When you buy a property you receive a deed from the seller. It's your lawyer's job to register the deed on the parcel register (an online system for all things land and property in Nova Scotia); the province charges a fee of $100 for registering a deed.
Deed Transfer Tax (1.5% of the Purchase Price)
In the CBRM the deed transfer tax is 1.5%. This is money collected from your lawyer when your lawyer registers your deed. On a $200,000 purchase this would be $3,000. There are some exemptions to this, but that's for another post.
Mortgage Registration Fee ($100)
Just like registering the deed in the online system, the province charges a fee of $100 to register your mortgage. Registering the mortgage is the responsibility of your lawyer and is required by your lender as a condition of providing the money for the purchase.
Title Insurance (Starting at $200) or Survey (Starting at $1,000)
Your lawyer will also recommend obtaining either title insurance or a survey of your lot. Title insurance protects you from certain defects with your land which could arise after the sale. A survey is prepared by a qualified Nova Scotia Land Surveyor and (most of the time) is preferable to title insurance because you can deal with problems proactively, rather than after you've already purchased the land. Your lender will require either title insurance or a survey to make sure they're covered in the event the land is something other than what everyone thought.
Legal Fees ($900 to $1,200 + HST)
Of course there are legal fees and of course they range. They range based on the lawyer and on the nature of the transaction. Ultimately, it's best to find a lawyer who is experienced with property transactions and who is attentive to your needs. This is likely the biggest transaction of your life.
Here's the total breakdown for Linda and Greg:

If I were representing Linda and Greg in this transaction, I would contact them ahead of time to let them know the final amount I needed from them in order to close. In this case, that would be $129,830.00 ($204,830 minus $75,000 in mortgage funds). If they obtained a bigger mortgage with a smaller down-payment the picture would look a bit different.
As you can see, the fees for Linda and Greg add up to $4,830.00. Most of that is the $3,000.00 Deed Transfer Tax owing to the municipality. You can see how Linda and Greg, as new home buyers might be surprised by these fees. When it comes to finances it's good to be prepared, especially when you're buying a home.
If you're selling a home, the fees are very different. We'll cover the fees associate with the sale side of a real estate transaction in another post.
How much is this going to cost me?
Fair question. You've worked hard to save the money for a downpayment on a house - now it's time for you to take the plunge and you're worried about surprises.
To make the whole process a little bit less intimidating, we've broken down the fees associated with a real estate transaction (from the buyer's side) so you can have an idea of how much the whole deal will actually cost.
Let's handle this with a case study.
Buyers: Linda & Greg
 |
| Linda & Greg - aren't they cute. |
Deed Registration Fee ($100)
When you buy a property you receive a deed from the seller. It's your lawyer's job to register the deed on the parcel register (an online system for all things land and property in Nova Scotia); the province charges a fee of $100 for registering a deed.
Deed Transfer Tax (1.5% of the Purchase Price)
In the CBRM the deed transfer tax is 1.5%. This is money collected from your lawyer when your lawyer registers your deed. On a $200,000 purchase this would be $3,000. There are some exemptions to this, but that's for another post.
Mortgage Registration Fee ($100)
Just like registering the deed in the online system, the province charges a fee of $100 to register your mortgage. Registering the mortgage is the responsibility of your lawyer and is required by your lender as a condition of providing the money for the purchase.
Title Insurance (Starting at $200) or Survey (Starting at $1,000)
Your lawyer will also recommend obtaining either title insurance or a survey of your lot. Title insurance protects you from certain defects with your land which could arise after the sale. A survey is prepared by a qualified Nova Scotia Land Surveyor and (most of the time) is preferable to title insurance because you can deal with problems proactively, rather than after you've already purchased the land. Your lender will require either title insurance or a survey to make sure they're covered in the event the land is something other than what everyone thought.
Legal Fees ($900 to $1,200 + HST)
Of course there are legal fees and of course they range. They range based on the lawyer and on the nature of the transaction. Ultimately, it's best to find a lawyer who is experienced with property transactions and who is attentive to your needs. This is likely the biggest transaction of your life.
Here's the total breakdown for Linda and Greg:

If I were representing Linda and Greg in this transaction, I would contact them ahead of time to let them know the final amount I needed from them in order to close. In this case, that would be $129,830.00 ($204,830 minus $75,000 in mortgage funds). If they obtained a bigger mortgage with a smaller down-payment the picture would look a bit different.
As you can see, the fees for Linda and Greg add up to $4,830.00. Most of that is the $3,000.00 Deed Transfer Tax owing to the municipality. You can see how Linda and Greg, as new home buyers might be surprised by these fees. When it comes to finances it's good to be prepared, especially when you're buying a home.
If you're selling a home, the fees are very different. We'll cover the fees associate with the sale side of a real estate transaction in another post.
|
| This post was written by Anna Manley. If you'd like to contact Anna you can send her an email: anna@manleylaw.ca |

Regardless of the size of your estate, the person you choose as your executor is going to have their work cut out of them.
It's the responsibility of the executor to deal with your estate assets in accordance with your will. In order to deal with those assets, your executor needs to be able to find them. It can be hard for executors to find assets like insurance policies or shares if you don't have the paperwork in one place at the time of your death. Finding estate assets after an estate has been dealt with can also add unnecessary time and expense to the handling of your affairs.
Rather than send your executor on a treasure hunt for your estate assets, you can take steps to make their job easier by keeping and updated list of your assets along side your will and other estate planning documents.

Remember, just like your will, the information inside the Estate Workbook is sensitive financial information and should be treated (and stored) with the utmost care. Keep the Estate Workbook in the same safe place you store your will and other estate planning documents.
Download and complete our Estate Workbook to make your executor's job easier.
|
| This post was written by Anna Manley. If you'd like to contact Anna you can send her an email: anna@manleylaw.ca |

CB Voices is a group of women stakeholders in Cape Breton Island. They believe in encouraging economic growth through fostering business, entrepreneurship, immigration, arts and culture, and tourism.
As part of their work, they created a series of videos called Women in Entrepreneurship. They interviewed female business owners from across the island in diverse sectors on their businesses and the how entrepreneurs can make a difference in the economy.
I was honoured to be included in the series along the outstanding female entrepreneurs. I was in good company and I encourage you to watch the interviews of all the other fantastic women - these are the people who are making a difference on our island.
I've posted my video below so you can hear what I had to say about my business, women in law, women in entrepreneurship, and the cultural shift happening on the island toward entrepreneurship.
Bonus: one of our office cats is featured.
Enjoy!
|
| This post was written by Anna Manley. If you'd like to contact Anna you can send her an email: anna@manleylaw.ca |
 |
| Click on the image to view full size infographic. |
Welcome to the 2018 Manley Law Real Estate Update. We do this every year to ensure our clients have a good idea of the housing trends on the island.

As of April 2018 there were 531 houses listed for sale in Cape Breton. That's down from 663 this time last year.

Of the houses currently listed, the least expensive was being offered for $19,000, while the most expensive home listed for sale was priced at $1,200,000.

The average price of a residential home in Cape Breton was $128,000 in the last quarter of 2017 - that's a 4.3% increase from the same time in 2016. The Average price for Nova Scotia is currently $240,000 and the average price for Canada is $494,309.

Residential home sales in Cape Breton increased 3.7% in the last quarter of 2017, compared with the fourth quarter of 2016. Compare that to the average increase of 9.1% for all of Nova Scotia.


In 2017, 2,808 people moved to Nova Scotia from other provinces - an increase of 11.4% from 2016. International immigration added 900 people to the province.
Pretty interesting stuff.

|
| This post was written by Anna Manley. If you'd like to contact Anna you can send her an email: anna@manleylaw.ca |

This is the Manley Law Estate Planning Guide. It's a good start when you're thinking about estate planning. The following is a list of what to think about before you come in to see us about your estate planning.
Who will be your executor?
The Executor is the person who will administer the terms of your will after your death. We recommend appointing an executor and an alternate executor (i.e. a person who would act in the event the executor is not able or unwilling to act). Both the executor and the alternate should be capable people who are likely to be around at the time of your death, but, and this is the most important requirement, the people you choose must be people you trust.
Who are the beneficiaries?
Beneficiaries are, no surprise, the people who benefit from your will.
Where a testator (the person signing the will) is married they may choose to give all they posses to their spouse in the event of their death, but this is not necessarily the case. A testator may choose to benefit their children, rather than their spouse, or to benefit one child more than another child. The testator has the power of decision, but this power is somewhat limited by a spouse’s interest in any property of the marriage. It is most common for couples with children to give all they possess to their spouse, but if the spouse dies before the testator the testator gives their possessions to either their children or the children’s trust (if the children are young).
Think about who you want to receive a benefit from your will and what you want that benefit to be.
Who will be the guardians of your children?
Who would you like to name as the guardian of your child or children? This can be a complicated question when it comes to blended families, but it’s prudent to identify one or more people you wish to be responsible for the future care of your children in the unlikely event both you and the other parent have died.
Also think about who you would like to handle the funds left to children. This can be your executor, the children’s guardian, or a third person as the children’s trustee. The children’s trustee (or trustees); this is the person who will manage the financial needs of the children and any money from your estate to be used for the care and maintenance of the children.
What about your assets?
What you have is almost as important as who you want to give it to. If you have any of following we can have a discussion on how to handle the item in question:
Real Property
Stocks / Investments
Business Interests
Pensions
Life Insurance
Expected Inheritance
Annuities
Valuable physical property (art, jewelry, collectables, etc)
Items of sentimental value (clothing, jewelry, books, photo albums, etc)
How you hold your assets is also important.
Have you named beneficiaries on your RRSP?
Do you hold property jointly with a spouse?
The answers to these questions can change and estate planning strategy.
Estate Planning isn’t just about wills.
A Power of Attorney and a Personal Medical Directive may be necessary to ensure your affairs are handled before death.
Power of Attorney
In the Power of Attorney you appoint an attorney and an alternate who can act as you would to manage your affairs - mostly of a financial nature. We often prepare an enduring power of attorney (one that will allow their spouse to act for them if they become incapacitated).
Think of who you would like to appoint as your attorney (this person is not necessarily your spouse) and also think of who you would like to be your alternate (the alternate will only act if your attorney cannot act or is unwilling to act). Your attorney should be someone who is responsible, trustworthy, and likely to be able and willing to act.
Personal Medical Directive
The Personal Medical Directive is a document in which you outline your values and wishes relating to the management of your care in the event you are not able to make these decisions yourself. The person you appoint, known as the delegate, can make decisions regarding your living arrangements, nutrition, treatment (as well as stopping treatment); however, your delegate cannot make active decisions regarding physician assisted death.
Think of who you would like to appoint as your delegate and also who would be a good alternate. Your delegate should be someone who is responsible, trustworthy, and likely to be able and willing to act. The delegate does not necessarily need to be the same person as your attorney.
Estate planning can be simple or complex, depending on what you have and what you'd like to see happen. Ultimately, it comes down to a discussion with your lawyer. This is a good list to get you started thinking about the process.
|
| This post was written by Anna Manley. If you'd like to contact Anna you can send her an email: anna@manleylaw.ca |


